Input VAT Deduction and Resource Misallocation: Resource Reallocation Driven by Non-Tax Wedges in China's "Business Tax Replaced by VAT" Reform
Speaker:Huang Ce, Professor, Southwestern University of Finance and Economics
Host:Nie Haifeng, Professor, Lingnan College
Time and Date:9:30, November 5, 2026 (Thursday)
Venue:Wang Dao Han Conference Room (101), Lingnan Hall
Language:Chinese
Abstract:
An incomplete VAT credit chain distorts production decisions, and services taxed on turnover and excluded from the VAT credit mechanism were once the most pervasive gap in that chain. China phased in the "business tax replaced by VAT" reform region by region during 2012–2013, progressively closing this gap. We find that in manufacturing industries more dependent on newly creditable service inputs, the dispersion of revenue productivity across firms falls, and this convergence operates entirely through labor allocation: only the marginal revenue product of labor converges, driven by improved matching between employment and operating revenue rather than by reduced dispersion in either alone. We then directly estimate the output gains from improved resource allocation. A one-standard-deviation increase in reform exposure raises industry aggregate output productivity by 1.0%–1.9%. Using the ratio of this gain to the estimated decline in variance, we identify the elasticity of substitution that is typically imposed a priori in the Hsieh–Klenow framework; estimates range from 1.9 to 2.6 across specifications and all reject an elasticity of 5. Yet the additional input credits introduced by the reform do not explain these allocation gains: observable non-creditable tax burdens account for less than 0.33% of the decline in dispersion, and firms never claiming input credits exhibit more than half of the aggregate convergence. Industry dependence on service inputs predicts the effect, firms' own service procurement does not, and firms do not shift from in-house provision to outsourced services. Nor do other observable factors account for it, including ten competing industry characteristics, local service-market thickness, or city- and province-level development. The improvement in resource allocation varies only with the industry's technological dependence on service inputs. Hence, under our research design, the transmission mechanism cannot be separately identified — rather than merely remaining unidentified.
Profile:
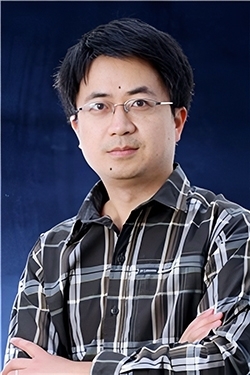
Huang Ce is a Professor and Doctoral Supervisor at the School of Public Finance and Taxation, Southwestern University of Finance and Economics. He holds a Ph.D. in Economics from the University of British Columbia. His main research areas include the evaluation and optimization of fiscal and tax policy, and search and matching theory. He has led a major project of the Sichuan Provincial Philosophy and Social Science Foundation and a project of the Ministry of Education's Humanities and Social Science Research Program. His research covers topics such as the "business tax replaced by VAT" reform, the super-deduction of R&D expenses, accelerated depreciation of fixed assets, tax competition, and resource allocation, with related work published in World Economic Papers, China & World Economy, Journal of the Asia Pacific Economy, Canadian Journal of Economics, and other journals. He has received the Sichuan Provincial Outstanding Achievement Award in Social Sciences.