即将开幕!第三届粤港澳大湾区计量经济学研究国际学术年会
第三届粤港澳大湾区计量经济学研究
国际学术年会
GBESG 2026
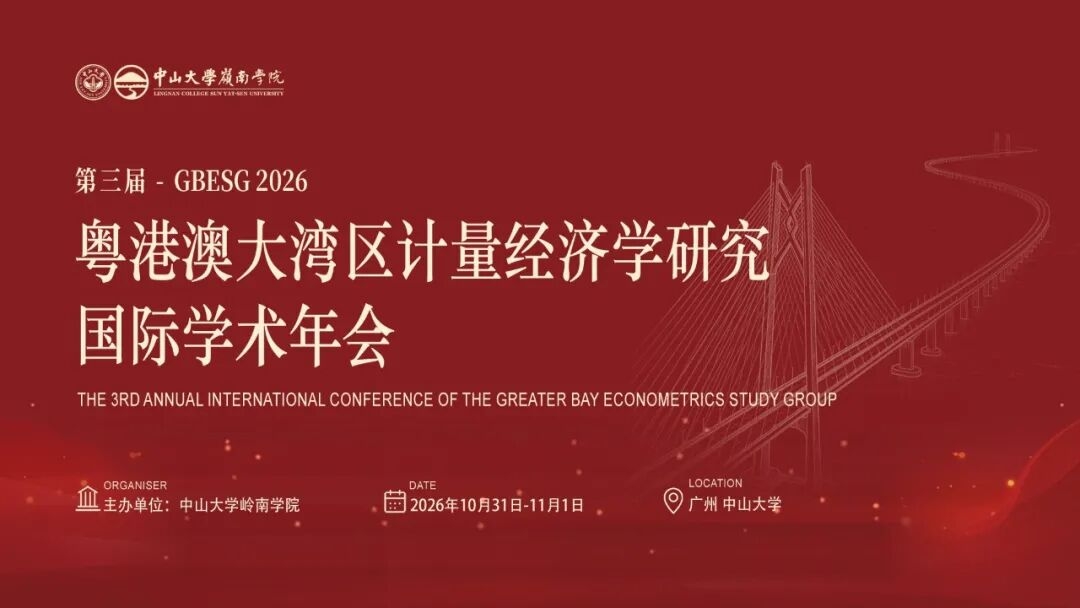
第三届粤港澳大湾区计量经济学研究国际学术年会(GBESG 2026)将于2026年10月31日至11月1日在中山大学广州校区南校园举办。年会由中山大学岭南学院与粤港澳高校经济学联盟承办,旨在为粤港澳大湾区计量经济学研究者搭建高水平国际学术交流平台,共同探讨微观计量经济学、宏观计量经济学、金融计量经济学及相关领域的最新进展与未来方向。
时 间2026年10月31日—11月1日
地 点中山大学岭南学院岭南堂
场 次27场,每场两篇报告,每篇30分钟
签到08:30–08:50
岭南堂一楼大堂
岭南堂302
主持 刘晓彬(中山大学)
致辞 周先波(中山大学),Jun Yu(澳门大学)
合影09:00–09:15
岭南堂北门
岭南堂302S01 序贯决策与矩阵因子模型
主持 王少平(华中科技大学)
报告一 09:15–09:45
Factor-Embedded Sequential Decision Models with Interactive Latent Heterogeneity
Degui Li · 澳门大学
报告二 09:45–10:15
Least Squares Estimators for Matrix Factor Models with Missing Values
Xu Han · 香港城市大学
岭南堂101S02 波动率预测与经验似然推断
主持 Yingying Li(香港科技大学)
报告一 09:15–09:45
Beyond the HAR: A New Benchmark for Volatility Forecasting
Jun Yu · 澳门大学
报告二 09:45–10:15
Online Empirical Likelihood
Zhentao Shi · 香港中文大学
岭南堂204S03 时空因果推断与空间动态面板
主持 周先波(中山大学)
报告一 09:15–09:45
Consistent Spatio-Temporal Causal Inference with Synthetic Error Models
Zudi Lu · 香港城市大学
报告二 09:45–10:15
Estimating Spatial Dynamic Panel Flow Data Models with Fixed Effects: A GMM Approach
虞吉海 · 北京大学
茶歇10:15–10:45
岭南堂三楼大厅
岭南堂302S04 粗糙波动率
主持 Jun Yu(澳门大学)
报告一 10:45–11:15
Intraday Volatility Dynamics
Carsten H. Chong · 香港科技大学
报告二 11:15–11:45
The Rough HAR Model
张晨 · 中山大学
岭南堂101S05 高维投资组合估计与均值方差优化
主持 李鲲鹏(首都经济贸易大学)
报告一 10:45–11:15
On Reference-Regulated Multiperiod Mean-Variance Portfolio Optimization in High Dimensions
Weichen Wang · 香港大学
报告二 11:15–11:45
Approaching the Frontier in Large Risky-Asset Universes: Direct Portfolio Estimation via CORE
Leheng Chen · 香港科技大学
岭南堂204S06 去偏机器学习
主持 Zhentao Shi(香港中文大学)
报告一 10:45–11:15
Debiased Machine Learning: Identification, Estimation, and Shape Constraints
陈齐辉 · 香港中文大学(深圳)
报告二 11:15–11:45
Automatic Debiased Machine Learning for Nonseparable Triangular Models
Ziwei Mei · 澳门大学
交流11:45–12:00
岭南堂302S07 分数随机波动与共同交易流
主持 Xinghua Zheng(香港科技大学)
报告一 13:30–14:00
A GMM Approach to Fractional Stochastic Volatility Model
肖炜麟 · 浙江大学
报告二 14:00–14:30
A Fine Lens on Common Trading Flows
Yi Ding · 澳门大学
岭南堂101S08 矩阵参数化与空间分位自回归
主持 虞吉海(北京大学)
报告一 13:30–14:00
A Balanced Parametrization of Correlation Matrices
童晨 · 厦门大学
报告二 14:00–14:30
Smoothed GMM Estimation of Spatial Quantile Autoregression
许杏柏 · 厦门大学
岭南堂204S09 因子模型与因果推断
主持 Degui Li(澳门大学)
报告一 13:30–14:00
High-Dimensional Mixed-Frequency Factor Models with Temporal Aggregation
王霞 · 中国人民大学
报告二 14:00–14:30
Causal Inference Using Factor Models
Peng Wang · 香港科技大学
茶歇14:30–15:00
岭南堂三楼大厅
岭南堂302S10 高频动量检验与跳跃强度预测
主持 Zudi Lu(香港城市大学)
报告一 15:00–15:30
Sign and Return Autocorrelation Tests for Time-Series Momentum in High-Frequency Data
Yang Zu · 澳门大学
报告二 15:30–16:00
Predictive Factor Model for Jump Intensities
Shiman Hu · 香港科技大学
岭南堂101S11 随机化检验与空间相关推断
主持 Xu Han(香港城市大学)
报告一 15:00–15:30
Randomization Tests in Randomized Saturation Designs
Liang Zhong · 香港大学
报告二 15:30–16:00
Matrix Completion, Factor Analysis and Treatment Effects in the Presence of Spatial Dependence
江弘毅 · 厦门大学
岭南堂204S12 异质面板I
主持 王霞(中国人民大学)
报告一 15:00–15:30
Unbalanced Heterogeneous Panel Data Models with Interactive Fixed Effects
王法 · 北京大学
报告二 15:30–16:00
Detecting Multiple Distributional Structural Breaks via Empirical Characteristic Functions and Shrinkage Estimation
高尚 · 厦门大学
岭南堂302S13 大语言模型辅助推断与异质溢出效应
主持 张一帆(中山大学)
报告一 16:05–16:35
Confidence-Driven Sequential Active Inference with Multi-LLM Annotations
Zihan Wang · 香港科技大学
报告二 16:35–17:05
Unobserved Heterogeneous Spillover Effects in Instrumental Variable Models
吴焕 · 厦门大学
岭南堂101S14 高频数据推断
主持 陈齐辉(香港中文大学(深圳))
报告一 16:05–16:35
Inference on the Realized Joint Laplace Transform of Volatility from High-Frequency Data with Microstructure Noise
Li Wang · 澳门科技大学
报告二 16:35–17:05
Ultra-High-Dimensional Spot Support Screening in Continuous-Time Regression
朱海斌 · 暨南大学
岭南堂204S15 异质面板II
主持 黄雯馨(上海交通大学)
报告一 16:05–16:35
Handling Endogenous Regressors in Correlated Heterogeneous Panels with Copula Augmented Mean Group Estimation
杨丽颖 · 深圳大学
报告二 16:35–17:05
Heterogeneous Panel Data Models with Regime Switching
黄雯馨 · 上海交通大学
岭南堂302S16 政策学习与市场均衡下的定向干预
主持 艾春荣(香港中文大学(深圳))
报告一 09:00–09:30
Debiased Policy Learning with Targeting Covariates Generated from Unstructured Data
解海天 · 北京大学
报告二 09:30–10:00
Policy Targeting with Market Equilibrium
Gyungbae Park · 香港中文大学(深圳)
岭南堂101S17 生育政策优化与分位回归
主持 王维国(东北财经大学)
报告一 09:00–09:30
Fertility Policy Optimization, Basic Research Investment, and Economic Growth: A Study from the Perspective of Investing in People
王维国 · 东北财经大学
报告二 09:30–10:00
A HAC-Robust Score Test for Quantile Regression
杨炳铎 · 广东财经大学
岭南堂204S18 全球通胀监测与区制依赖的货币传导
主持 陈创练(暨南大学)
报告一 09:00–09:30
Real-time Monitoring in Panel Quantile Models with an Application to Global Inflation
王奕人 · 湖南大学
报告二 09:30–10:00
Instrument Informativeness and Regime-Dependent Monetary Transmission
史健杰 · 湖南大学
茶歇10:00–10:30
岭南堂三楼大厅
岭南堂302S19 期权定价与已实现贝塔预测
主持 程明勉(中山大学)
报告一 10:30–11:00
Option Pricing with Dynamic Conditional Skewness and Jump
梁方(Fang Liang) · 中山大学
报告二 11:00–11:30
Forecasting Realized Beta and Its Components: Machine Learning, Information Structure, and Coherent Reconciliation
罗嘉雯 · 华南理工大学
岭南堂101S20 分位偏相关与两步政策评估
主持 史炜(暨南大学)
报告一 10:30–11:00
Quantile Partial Correlation for Growth Vulnerabilities
陈弘琦 · 湖南大学
报告二 11:00–11:30
When Policy Changes Productivity Dynamics: Validity and Bias Transmission in Two-Step Policy Evaluation
Shigang Li · 中山大学
岭南堂204S21 波动率预测与空间面板
主持 杨海生(中山大学)
报告一 10:30–11:00
Double-Attention Is All You Need: Generalized HAR for Volatility Forecasting
Jinbo Cai · 新南威尔士大学
报告二 11:00–11:30
Spatial Interactions in Threshold Dynamic Panel Regression with Two-Way Fixed Effects
白虎杰(Hujie Bai) · 中山大学
交流11:30–12:00
并行分会场813:30–14:30
岭南堂302S22 工具变量推断与聚类稳健检验
主持 连玉君(中山大学)
报告一 13:30–14:00
An Improved Inference for IV Regressions
Pengjin Min · 新加坡管理大学
报告二 14:00–14:30
Testing One-Way versus Two-Way Clustering: Non-Normal Limits and Bootstrap Inference
Zhou Wu · 浙江大学
岭南堂101S23 分位时间序列结构变化与网络形成
主持 李捷瑜(中山大学)
报告一 13:30–14:00
Testing for Smooth Structural Changes in Quantile Time Series Models
Ang Li · 厦门大学
报告二 14:00–14:30
Moment Restrictions for Dyadic Network Formation Models with Nontransferable Utility
Hanping Chen · 香港中文大学(深圳)
岭南堂204S24 矩阵因子模型与GMM资产定价检验
主持 陈良源(中山大学)
报告一 13:30–14:00
The Zero-Point Trap in GMM-Based Asset Pricing Tests: Diagnostics and Remedies
Yuqi Wang · 厦门大学
报告二 14:00–14:30
A Nonlinear Factor Model for Reduced-Rank Matrix Time Series
Longcan Li · 墨尔本大学
茶歇14:30–14:45
岭南堂三楼大厅
并行分会场914:45–15:45
岭南堂302S25 局部投影、弱识别与波动率预测
主持 肖炜麟(浙江大学)
报告一 14:45–15:15
Recursive Shrinkage Local Projection
Chengwang Liao · 香港中文大学
报告二 15:15–15:45
Weak Identification in News-Jump Regressions
Jiezheng Wei · 新加坡管理大学
岭南堂101S26 高频因子与高维组合优化
主持 张晨(中山大学)
报告一 14:45–15:15
High-Frequency Factor Models with Group Structure Learned from a Characteristics Tensor
Jiayan Li · 香港城市大学
报告二 15:15–15:45
Incorporating Return Prediction in High-dimensional Mean-Variance Portfolio Optimization
Ruizhao Huang · 香港科技大学
岭南堂204S27 社会互动与股票共跳网络
主持 刘晓彬(中山大学)
报告一 14:45–15:15
Social Interactions Models with Latent Structures
Yapeng Zheng · 香港中文大学
报告二 15:15–15:45
Modeling Multilayer Stock Co-jump Networks with Dependent Edges
Luwen Zhang · 澳门科技大学
岭南堂302
主持 刘晓彬(中山大学)
致辞 艾春荣(香港中文大学(深圳));Jun Yu(澳门大学)